
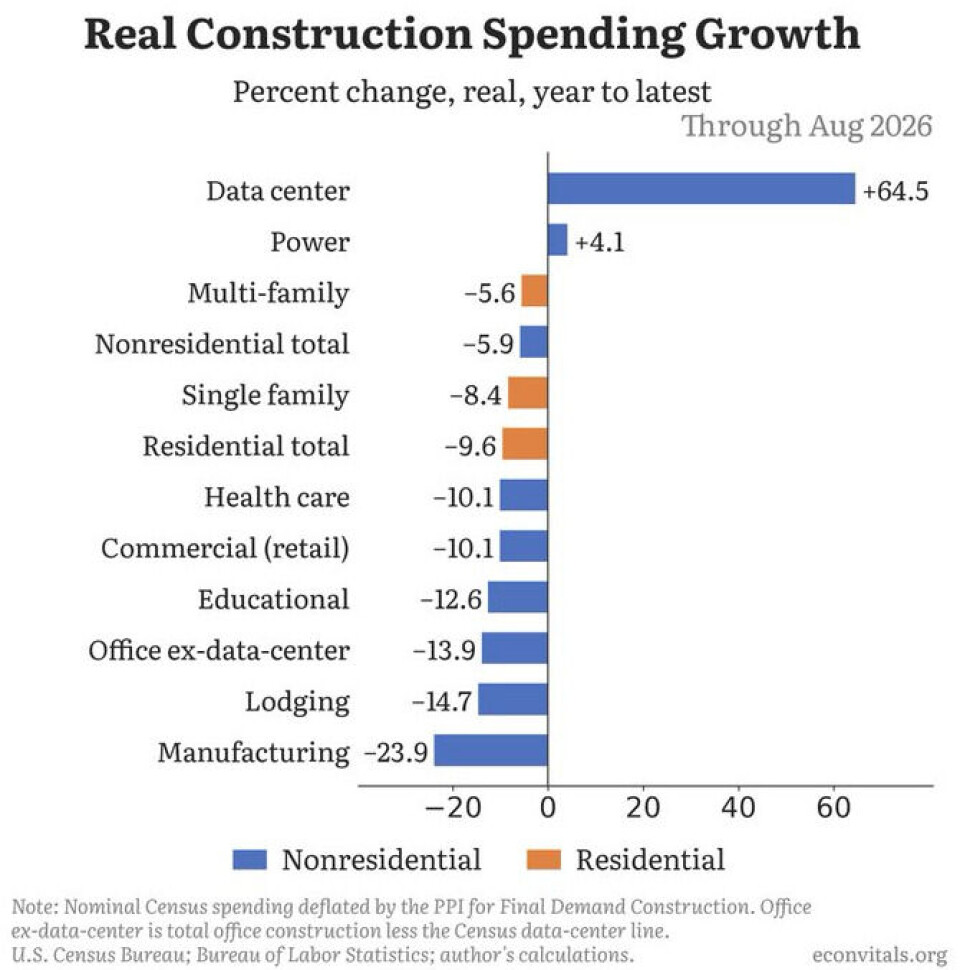
Looking at the historical trajectory provided by the U.S. Census Bureau and analyzed by researchers at Oxford University’s Our World in Data project, the inflection point is clear. When adjusted for inflation to 2021 dollars, spending on datacenter construction remained relatively stable for nearly a decade. However, that changed abruptly in November 2022. The launch of high-profile generative AI models acted as a starting gun, and since that moment, the market has moved into a period of vertical acceleration. This trend is almost entirely driven by private sector investment; while federal, state, and local governments do maintain their own datacenters, their spending is a mere fraction of the capital being deployed by hyperscalers, cloud service providers, and specialized AI model developers.
To understand where this trend is headed, a detailed forecast from analysts at Jeffries, produced in collaboration with market research firm Aterio, provides a sobering look at the limitations of the "bull case" for AI. While the industry is flush with ambitious announcements and massive "planned" projects, the reality of execution is far more complicated.
According to Jonathan Petersen, managing director at Jeffries, the AI industry is currently grappling with a fundamental "datacenter problem." The demand for inference and the training of next-generation frontier models is simply outstripping the ability of developers to bring physical capacity online. Jeffries’ dataset tracks approximately 65 gigawatts (GW) of IT capacity currently under construction in North America—a figure that represents roughly 140 percent of the total currently installed capacity. Even more ambitious is the pipeline of future announced projects, which totals 361 GW, or about 760 percent of the current footprint.
However, Petersen and his team are appropriately skeptical about how much of this pipeline will actually reach completion. The transition from a project "announcement" to an "online" facility is fraught with delays and cancellations. Jeffries expects approximately 12.9 GW of new capacity to come online in 2026, rising to 18 GW in 2027. These figures, while massive, represent a significant haircut compared to the aspirations of the world’s largest technology companies.
The gap between what hyperscalers want to build and what they are likely to achieve is widening. For 2026, the industry has largely locked in its plans, with hyperscalers aiming for 6.21 GW of capacity. But as we look further into the future, the projections diverge sharply. By 2028, hyperscalers have expressed a desire to build out 10.13 GW of capacity, yet Jeffries anticipates only about 6.54 GW will actually be completed. By 2029, the disparity becomes even more pronounced: against an aspirational goal of nearly 18 GW, analysts expect only 5.86 GW to reach the finish line. By the turn of the decade in 2030, the expected build-out drops to 4.46 GW, even as planned projects remain significantly higher.
 Enterprise Tech & Infrastructure
AMD Acquires World Labs for $8.2 Billion to Rival Nvidia in the Frontier of World Models
In a massive strategic move designed to reshape its standing in the...
 Enterprise Tech & Infrastructure
Decoding the True Cost of Amazon S3: Why Storage Class Rates Are Only Half the Story
For enterprise IT leaders and cloud architects, the promise of Amazon S3...
 Enterprise Tech & Infrastructure
Bridging the Gap in Data Center Convergence: The Evolving Role of Fibre Channel over Ethernet
As data centers face unprecedented pressure to handle massive workloads driven by...







