
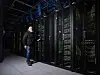
CoreWeave, the specialized cloud provider that has effectively crowned itself the king of the "neoclouds" by focusing almost exclusively on high-end artificial intelligence processing, continues to be a polarizing figure in the technology and finance sectors. As the company navigates the turbulent waters of the generative AI boom, it remains a focal point for both bullish investors who see it as the backbone of the next industrial revolution and bearish critics who worry about its aggressive leverage. The company’s recently released financial results for the third quarter of 2026 provide a complex picture of a business that is simultaneously scaling at a breakneck pace, exercising immense pricing power, and grappling with the massive costs of its own rapid expansion.
The central narrative of CoreWeave’s current fiscal health is one of supply and demand. In a world where the hunger for Graphics Processing Units (GPUs) far outstrips the available supply, CoreWeave occupies a privileged position. This persistent undersupply has allowed the company to do something rarely seen in the maturing cloud computing market: significantly raise prices on aging hardware. As organizations scramble to secure the compute power necessary to train increasingly massive large language models (LLMs) and run inference workloads at scale, the market value of even "vintage" GPUs in the CoreWeave fleet has seen a dramatic upward trajectory.
During a detailed review of the company’s performance for the quarter ending in September 2026, CoreWeave co-founder and chief executive officer Michael Intrator highlighted how the company is capitalizing on these favorable market dynamics. Intrator revealed that in July, CoreWeave implemented a broad-based price increase of approximately 25 percent across its various stock-keeping units (SKUs). This was not a one-time adjustment; the company followed up with another 10 percent increase later in the same quarter. According to Intrator, this upward momentum in pricing has carried over into the fourth quarter, more than offsetting the rising operational costs associated with running a global network of high-density datacenters.
The economics of CoreWeave’s fleet management are particularly revealing. The company is currently operating a two-tiered strategy to maximize returns. On one hand, it is allocating a significant portion of its capacity to short-term, opportunistic contracts where the extreme demand allows for premium pricing. In these scenarios, CoreWeave is commanding prices in excess of $40 million per megawatt annually. On the other hand, the company continues to sign four- and five-year long-term contracts for new infrastructure, which are currently pricing in the range of $20 million to $25 million per megawatt.
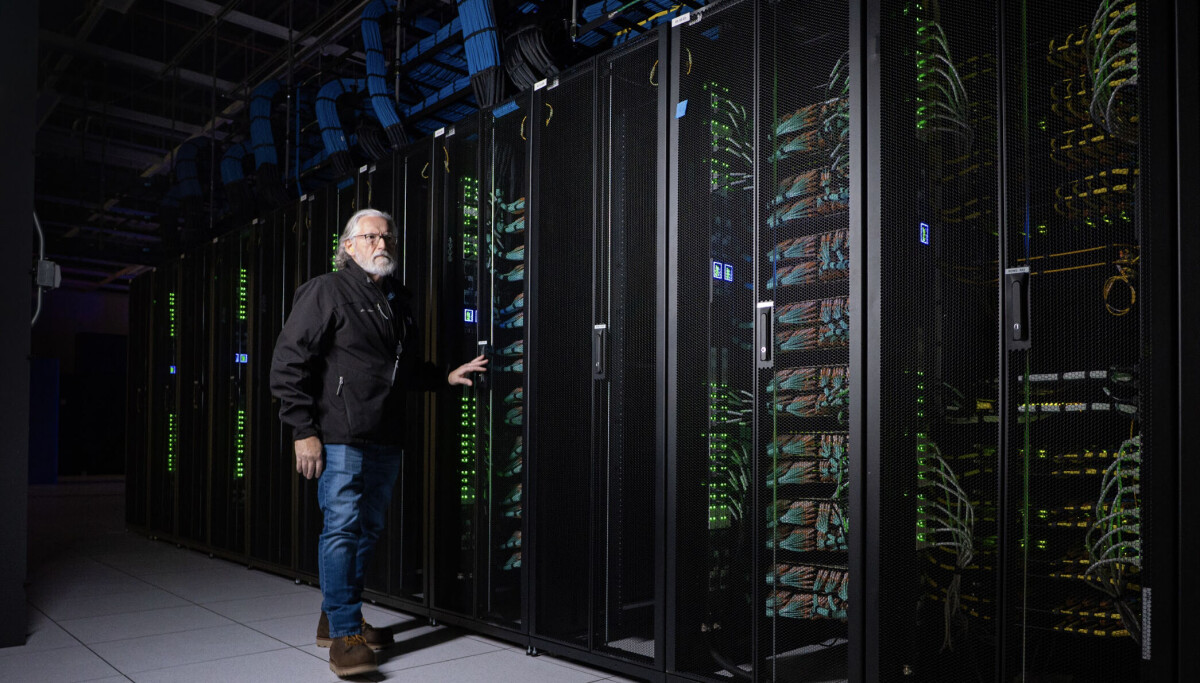
While the long-term commitments provide the financial visibility and predictability necessary to support CoreWeave’s massive capital expenditure (capex) program, the short-term contracts allow the company to act as a high-frequency trader of compute power, capturing the "spread" created by immediate supply crunches. Intrator noted that the company carefully weighs the trade-off of every contract, assessing the full lifecycle economics of the investment, from the cost of financing the hardware to the long-term revenue potential and the immediate operational overhead.
One of the most surprising aspects of the Q3 2026 report is the continued profitability of older hardware. Intrator pointed out that rental prices for Nvidia’s "Ampere" A100 GPUs rose by 30 percent sequentially during the third quarter. Even more impressively, rental prices for the "Hopper" H100 and H200 GPUs surged by 50 percent in the same period. To put this in perspective, the A100 GPUs are now roughly six and a half years old, having first hit the market in mid-2020. The H100s are now four years old. In the traditional world of enterprise IT, hardware of this age is typically considered legacy and is often being phased out.
 Enterprise Tech & Infrastructure
Decoding the Hidden Costs of Amazon S3: Why Storage Rates Are Only the Surface of Enterprise Cloud Spending
In the complex landscape of enterprise cloud infrastructure, Amazon S3 (Simple Storage...
 Enterprise Tech & Infrastructure
Navigating the Shift to Software-Defined Storage: Essential Strategies for Modern Enterprise Data Management
The landscape of enterprise data storage is undergoing a fundamental transformation. As...
 Enterprise Tech & Infrastructure
Bridging the Gap in Data Center Convergence: The Evolving Role of Fibre Channel over Ethernet
As data centers face unprecedented pressure to handle massive workloads driven by...







