
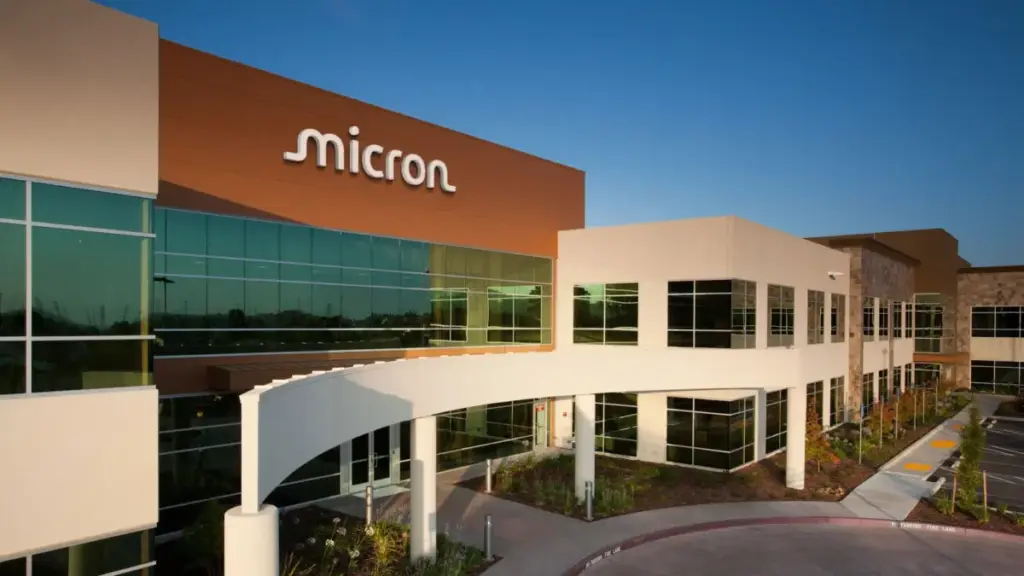
The global semiconductor landscape is facing a prolonged period of volatility as Micron Technology, one of the world’s leading manufacturers of memory and storage solutions, warns that the current supply-demand imbalance is far from over. In a series of disclosures that have sent ripples through the enterprise IT and consumer electronics sectors, the company signaled that the memory shortage—which has already significantly inflated the cost of servers, storage arrays, and personal computers—is expected to intensify through 2027 and into 2028.
For organizations that had hoped for a stabilization of hardware costs in the near term, the outlook remains challenging. Micron’s leadership indicated that the fundamental pressures driving prices upward are not only persisting but are likely to become more acute in the coming years. This projection pushes back earlier industry expectations, which had tentatively pointed toward a market correction and a return to equilibrium by 2028. Instead, the industry is now preparing for a "much tighter" environment than previously anticipated.
A Market in Structural Deficit
The primary driver behind this somber outlook is a structural gap between the surging demand for high-performance memory and the industry’s ability to bring new production capacity online. During the company’s fiscal fourth-quarter earnings call, Micron CEO Sanjay Mehrotra provided a candid assessment of the road ahead.
“We expect memory and storage supply-demand conditions to be much tighter in calendar 2027 and 2028 than they were in 2026,” Mehrotra stated in his prepared remarks. He emphasized that despite the industry’s aggressive plans to expand cleanroom space and build new fabrication facilities, the timeline for these investments to impact the market is measured in years, not months.
The complexity of semiconductor manufacturing means that simply building a factory does not provide an immediate solution to a global shortage. Mehrotra noted that production from new DRAM (Dynamic Random Access Memory) and NAND flash fabrication facilities requires a significant period to "ramp" up. According to the CEO, it typically takes several quarters after the initial output for a new facility to produce volumes that are "meaningful" enough to influence global supply levels. Consequently, the "line of sight" regarding when the market will finally return to a state of balance remains obscured.
Higher Prices and Diminishing Configurations
The financial impact of this shortage is already being felt across the supply chain. Micron CFO Mark Murphy highlighted that the company’s internal inventory levels remain "extremely tight," leaving little room to absorb fluctuations in demand. This scarcity has directly translated into aggressive price increases. In the most recent fiscal quarter, Micron’s DRAM prices rose by a percentage in the high teens, while NAND prices saw a dramatic surge of approximately 30%.
These internal metrics from Micron are mirrored by broader market research. TrendForce, a Taiwan-based firm that tracks semiconductor pricing, issued a report on September 30 forecasting continued upward pressure on contract prices. TrendForce expects conventional DRAM prices to climb an additional 10% to 15% in the fourth quarter of the current year compared to the third. NAND flash prices are projected to rise even faster, with expected increases between 15% and 20%. While the firm noted that the rate of increase might be slowing compared to previous spikes, the underlying reality remains an undersupplied market where sellers hold the upper hand.
The ripple effects of these component price hikes are reaching the end-user. Research firm IDC warned earlier this year that PC buyers should prepare for "volatile territory." In a June forecast, IDC projected that the average selling price for personal computers will rise by 17% in 2026.
Beyond just paying more, enterprises and consumers may also be getting less for their money. TrendForce has observed a notable shift in server configurations as OEMs (Original Equipment Manufacturers) and cloud service providers attempt to mitigate rising costs. Since the first half of 2026, there has been a documented move away from high-capacity 96GB and 128GB memory modules toward more modest 32GB and 64GB modules. This trend confirms earlier warnings from analysts that enterprise PC and server refreshes would likely be characterized by both higher price tags and downgraded specifications.
Supply Committed Years into the Future
One of the most striking revelations from Micron’s recent disclosures is the extent to which future production is already spoken for. The company has already committed more than 75% of its entire 2027 output to customers. Furthermore, Mehrotra revealed that the majority of current discussions with major clients are no longer about immediate needs but are focused on securing supply for 2028.
To manage this environment, Micron is increasingly relying on what it calls Strategic Customer Agreements (SCAs). These are multiyear, "take-or-pay" contracts that guarantee a certain volume of supply for the buyer while providing a predictable revenue stream for the manufacturer. However, these agreements come at a premium. Mehrotra noted that any new discussions regarding SCAs involve pricing negotiated at higher levels, reflecting the prevailing market conditions and the long-term bullish outlook for memory costs.
This "lock-in" strategy is not limited to Micron. TrendForce reports that several major cloud providers have signed similar long-term agreements with various memory makers to ensure their data centers remain operational. This leaves smaller buyers—those without the scale or capital to sign multiyear, take-or-pay deals—to bear the brunt of spot-market price increases.
Strategic Advice for IT Leaders
As the "memory squeeze" tightens, Chief Information Officers (CIOs) and IT procurement managers are being forced to rethink their infrastructure strategies. Neil Shah, vice president of research at Counterpoint Research, suggests that the current outlook requires a shift from routine purchasing to strategic asset management.
“CIOs will have to be prudent about which equipment to upgrade and which to stretch to maintain cost efficiencies,” Shah said. He noted that the standard three-year refresh cycle may no longer be financially viable for all departments. For "back-office" functions and routine file servers, extending the lifecycle of hardware from three to five years is a relatively "harmless" way to save capital.
However, Shah warned against a blanket policy of delaying upgrades. For "core infrastructure" and high-performance "engineering seats," failing to refresh hardware on time can lead to a "backfire" effect. Aging equipment in these critical areas can result in significant productivity losses, lack of software compatibility, and an increased risk of hardware failure.
Shah also offered a stern warning regarding the secondary or "legacy" memory market. As manufacturers like Micron shift their production lines to more profitable and in-demand technologies like High-Bandwidth Memory (HBM) and DDR5, older standards like DDR4 are becoming increasingly scarce.
“If you buy legacy platforms today to shave 10% off upfront server costs, you’re buying into systems which won’t have serviceable parts two years from now,” Shah cautioned. Instead of seeking savings through older hardware, he recommended that enterprises focus on optimization.
According to Shah, many enterprises waste between 30% and 50% of their purchased memory by provisioning for peak loads that rarely occur. He suggests that before committing to expensive new hardware, organizations should look at "right-sizing" virtual machines, utilizing "quantization" for AI models to reduce their memory footprint, and batching workloads more efficiently. “CIOs should think about optimizing on the silicon already in place,” he added.
The Vendor Response
The hardware vendors that sit between memory makers and enterprise customers have offered little in the way of financial relief. Lenovo, one of the world’s largest PC and server manufacturers, indicated that it is prepared to pass these costs directly to the market.
During an August earnings call, Lenovo Chairman and CEO Yuanqing Yang echoed Micron’s sentiment, stating that he expects memory demand to continue rising and supply to remain constrained through at least the end of 2027. Yang was clear about how Lenovo would handle the situation: “When the material costs rise, we can adjust the pricing at the front end in a timely manner.”
While the PC market as a whole is expected to shrink in terms of unit volume—with Lenovo’s Intelligent Devices Group predicting a 15% drop in the six months leading to March—the demand for high-end enterprise servers remains robust. Ashley Gorakhpurwalla, president of Lenovo’s Infrastructure Solutions Group, noted that a "strong server refresh cycle" is currently underway, driven largely by the global push for AI and modernized data center capabilities.
Other major players in the hardware space, including Dell, HPE, Cisco, and Supermicro, did not provide comments on how they intend to navigate the projected 2027-2028 shortage. However, the consensus among analysts is that the entire industry is moving toward a "higher-for-longer" pricing environment for memory-dependent hardware.
As the industry moves toward the end of the decade, the narrative has shifted from a temporary post-pandemic supply chain glitch to a long-term structural reality. With most of the 2027 supply already spoken for and prices continuing their upward trajectory, the "memory squeeze" is set to remain a defining challenge for the global IT economy.
 Small Business IT & Cloud Computing
AI-Driven Cyberattacks Target Online Retailers at a Cost of Just $25 Per Breach
The landscape of cybersecurity is undergoing a fundamental shift as the barrier...
 Small Business IT & Cloud Computing
Meta’s AI Vision Is the Best in the Industry—But Its History Makes It Impossible to Trust
We are currently standing on the precipice of a fundamental revolution in...
 Small Business IT & Cloud Computing
Tech Manufacturing Faces Triple Threat of Surging Component Costs, Logistics Strain, and Global Sovereignty Shifts
The consumer electronics landscape is currently navigating a period of unprecedented volatility,...







